Pet Insurance in Santa Cruz County: What Every Pet Owner Should Know
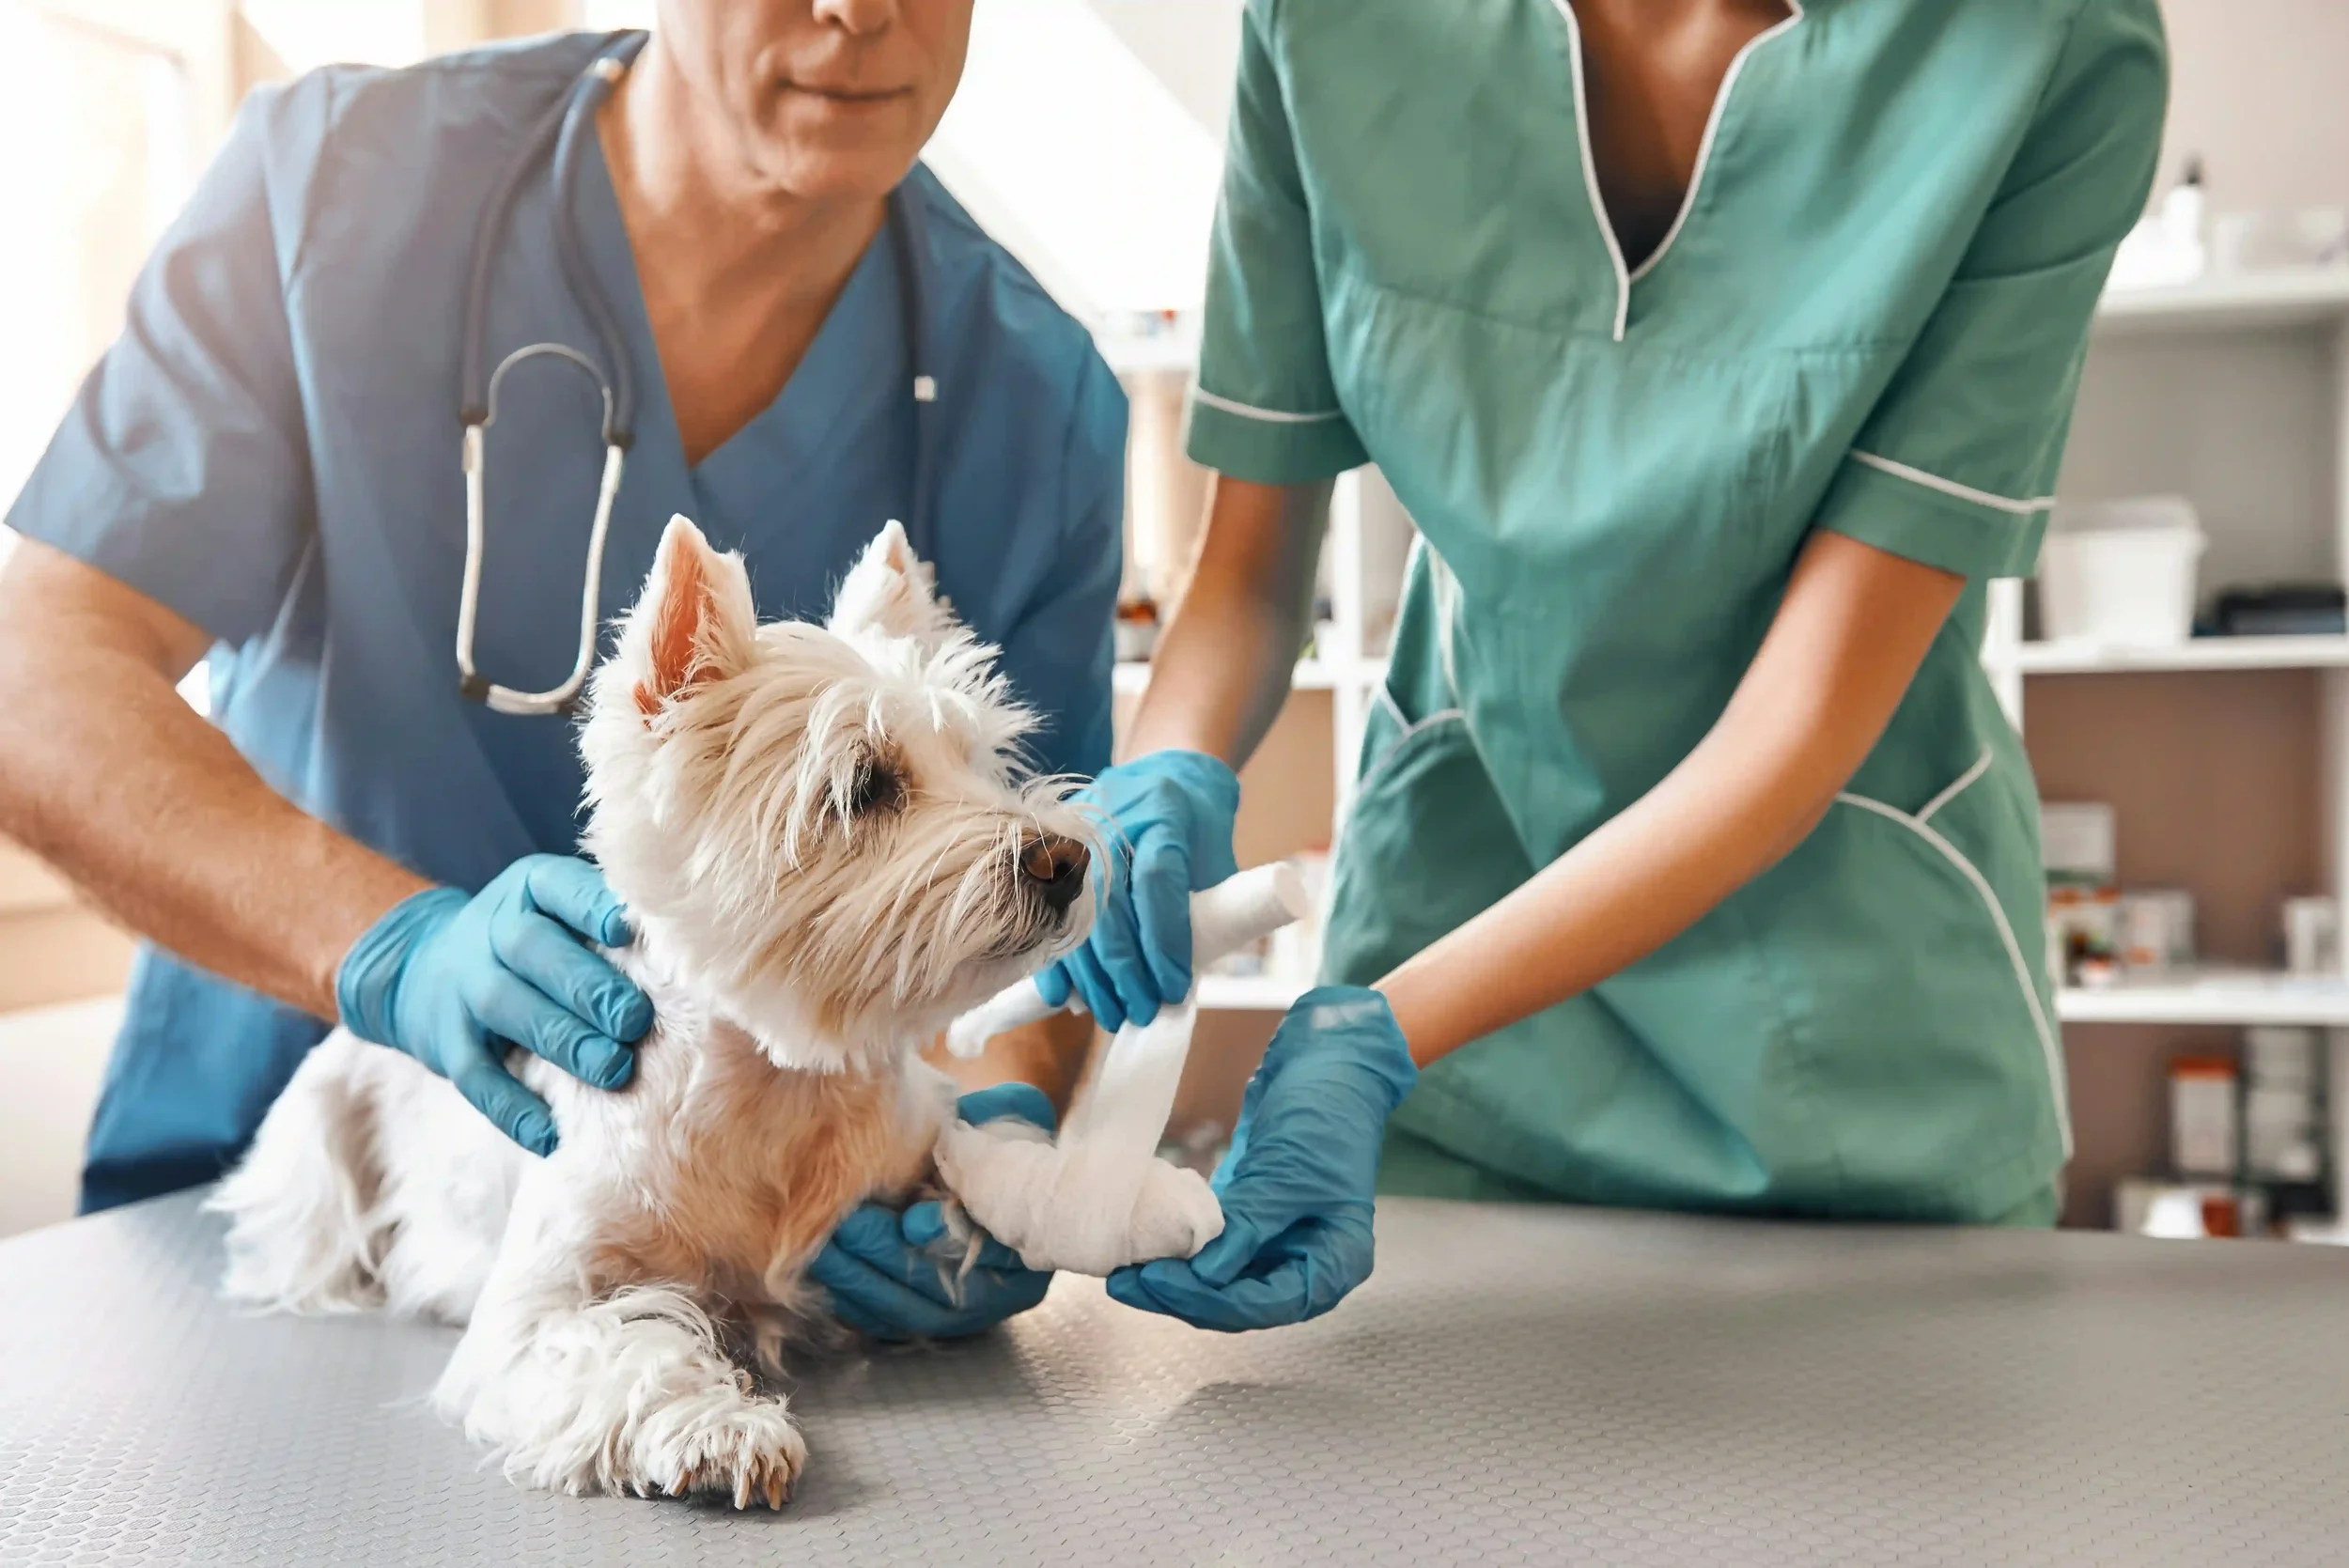
If you have a dog, a cat, or another beloved animal at home, you already know that veterinary care is not cheap. A routine visit is manageable. But an unexpected illness, an injury, or a serious diagnosis can generate a bill that runs into several thousand dollars before you have had time to think it through.
Pet insurance exists to help with exactly that scenario. It is one of the fastest-growing segments of the personal insurance market, and for families throughout Watsonville, Santa Cruz County, and Monterey County, it is a coverage worth understanding before an emergency visit makes the decision for you.
What Pet Insurance Actually Covers
Pet insurance works differently from human health insurance, and understanding the structure upfront avoids surprises later.
Most pet insurance policies work on a reimbursement model. You pay the veterinarian at the time of service, submit a claim to your insurer, and receive reimbursement based on your plan’s coverage terms. You choose your deductible, your reimbursement percentage, and your annual coverage limit when you enroll, and those choices directly affect your monthly premium.
Coverage varies by policy and carrier, but most standard pet insurance plans cover the following categories.
Accidents. Injuries from falls, car accidents, ingesting foreign objects, lacerations, and other unexpected physical incidents. Accident coverage is included in virtually every pet insurance plan and is typically the least expensive standalone option.
Illnesses. Diagnosis and treatment of health conditions including infections, digestive issues, skin conditions, respiratory illness, cancer, diabetes, and many chronic conditions. Illness coverage is where pet insurance delivers its greatest financial value given how costly ongoing treatment can be.
Emergency and Specialty Care. Emergency veterinary visits, specialist consultations, surgery, hospitalization, and diagnostic imaging such as X-rays, MRIs, and ultrasounds. These are among the highest-cost veterinary services and among the most important to have covered.
Hereditary and Congenital Conditions. Many plans cover conditions that are breed-specific or present from birth, though coverage terms and waiting periods vary. This is an important consideration for owners of breeds with known health predispositions.
Some plans also offer optional wellness coverage as an add-on, which helps offset the cost of routine preventive care including annual exams, vaccinations, flea and tick prevention, and dental cleanings. Wellness add-ons are not insurance in the traditional sense but they can make routine care more predictable and affordable.
What Pet Insurance Typically Does Not Cover
Understanding exclusions is just as important as understanding what is covered. Most pet insurance policies exclude the following.
Pre-existing conditions. This is the most significant exclusion in most policies. Any condition that existed or showed symptoms before your policy’s effective date is typically not covered. This is the strongest argument for enrolling your pet while they are young and healthy rather than waiting until a health issue arises.
Elective procedures. Cosmetic procedures, elective surgeries, and breeding-related costs are generally excluded.
Preventive care under a standard plan. Routine wellness visits, vaccinations, and preventive medications are typically not covered under a standard accident and illness policy without a wellness add-on.
Waiting periods also apply to most policies. There is typically a short waiting period after enrollment before accident coverage activates, and a longer waiting period before illness coverage takes effect. Enrolling before a health issue appears and before waiting periods become a factor is the most effective way to maximize the value of a pet insurance policy.
Why Veterinary Costs in California Make Pet Insurance Worth Considering
California consistently ranks among the most expensive states for veterinary care, and the Central Coast is no exception. The cost of living, labor expenses, and the concentration of specialty veterinary practices in the region all contribute to rates that are meaningfully higher than the national average.
An emergency visit to a veterinary urgent care clinic in Santa Cruz County can run several hundred dollars for a straightforward case and significantly more for anything requiring diagnostics, surgery, or overnight care. A cancer diagnosis in a dog or cat can generate treatment costs in the range of five to fifteen thousand dollars depending on the type and course of treatment chosen.
For most families, those numbers represent a genuine financial decision point. Pet insurance does not eliminate that decision, but it changes what the options look like when the moment arrives.
When to Enroll: The Earlier the Better
The single most important thing to know about pet insurance timing is that the best time to enroll is when your pet is young and healthy.
Pre-existing condition exclusions mean that any health issue your pet develops before you enroll will not be covered. A dog who develops hip dysplasia before you purchase a policy will not have that condition covered under most standard plans. A cat who has been treated for urinary issues will find those excluded from coverage going forward.
Enrolling a puppy or kitten in the first year of their life gives you the broadest possible coverage because there is no health history to exclude. Premiums are also lower for younger animals and tend to increase as pets age, making early enrollment the most cost-effective approach over the life of the policy.
If your pet is already a few years old, coverage is still available and still worth evaluating. The pre-existing condition exclusions will be more of a factor, but accident coverage and coverage for new conditions going forward still provide real value.
How Pet Insurance Fits Into Your Overall Insurance Picture
Pet insurance is a personal lines product that sits alongside your homeowners, auto, and umbrella coverage as part of your household’s financial protection plan. For families in the Pajaro Valley who already review their personal insurance regularly, adding a pet insurance conversation to that review is a natural step.
If you have not looked at your overall personal coverage recently, our annual personal insurance checklist for Santa Cruz County residents is a good place to start. Pet insurance is one more item worth adding to that list.
How KBK Can Help You Explore Pet Insurance Options
At KBK Insurance Agency, we work with families throughout Watsonville, Santa Cruz County, Monterey County, and the Pajaro Valley on their personal insurance needs. Pet insurance is a product we can help you explore, and we are happy to have a straightforward conversation about what the options look like and whether a policy makes sense for your household.
Our team has been helping Central Coast families protect what matters most since 1908. A pet is very much part of that picture for most families we work with.
If you have questions about pet insurance or want to find out what coverage options are available for your animal, reach out at www.kbkinsurance.com/contact or call us at 831-724-1085.
Pet insurance coverage terms, exclusions, waiting periods, and reimbursement structures vary by carrier and policy. Speak with a licensed insurance professional to understand what applies to your specific situation and pet.